How many shares should you buy? Comparing five position sizing models.
Two traders can take the exact same setup — same stock, same entry, same stop — and end up with completely different outcomes. The difference usually isn't the idea. It's how much of it they bought.
Most trading education covers finding stocks, reading charts and timing entries. Position sizing — deciding how many shares to buy — gets a sentence, if that.
That's backwards. A slightly early or late entry can still work. A wrong size lets one bad trade undo weeks of good ones. Sizing is what protects your capital when an idea is wrong.
A risk-aware decision engine doesn't pick the stock. It turns your risk limits and conviction into a share count you can defend, the same way every time.
Already know the theory? Jump to the calculator and size your own trade
The example trade
One setup, used throughout this article so the numbers stay comparable. It's a long trade in SAP, with illustrative prices, set up in Krino exactly as below:
| Portfolio capital | €100,000 |
| Max risk per trade | 1.2% |
| Max position exposure (this symbol) | 40% → €40,000 |
| Entry price | €205 |
| Stop-loss | €188 |
| Take-profit | €236 |
| Risk per share (205 − 188) | €17 |
| Reward per share (236 − 205) | €31 |
| Risk / Reward | 1 : 1.82 |
Same setup, five sizing models, five very different positions. Krino computes all five side by side. Here is this trade:
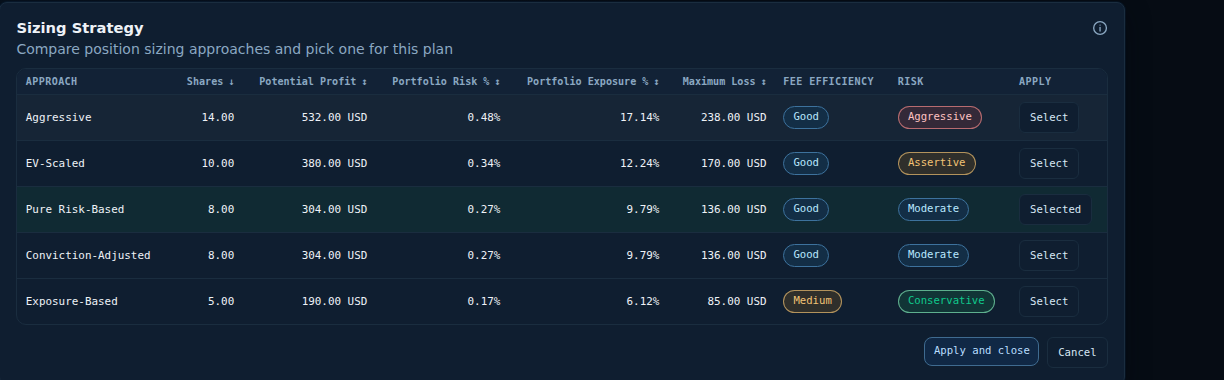
Each model, formula first:
1Pure Risk-Based Sizing
Decide in advance how much money you're willing to lose. Size the position so a full stop-out costs exactly that — nothing more.
| Allocated capital = 100,000 × 40% max position exposure | €40,000 |
| Risk % | 1.2% |
| Risk amount = 40,000 × 1.2% | €480 |
| Shares = 480 / 17 | ≈ 28 |
| Position value | ≈ €5,740 |
| Maximum loss | ≈ €476 |
| Potential profit | ≈ €868 |
- Strong discipline
- Excellent capital preservation
- Same money at risk on every trade
- Can produce very small positions
- Feels restrictive on high-conviction ideas
Most professional risk desks start here: the position is built from what you can afford to lose, not how much you want to own. It's the Pure Risk-Based row in the screenshot above.
Pure Risk-Based sizing answers "how much can I afford to lose" first, and lets share count fall out of that — not the other way around.
2Conviction-Adjusted Sizing
Krino's default. Starts from the same risk cap as Pure Risk-Based, then shrinks it by how strongly your own rules agree with each other on this setup.
Where "conviction" actually comes from
Every indicator you've configured — RSI, MACD, an EMA/SMA crossover, Bollinger Bands, whatever's weighted in your rule set — votes toward Buy or Sell, each with its own weight. Conviction is just the margin between the two sides, as a share of the total weight in play:
Rules that all point the same way push conviction toward 1.0; a near-even split pushes it toward 0. The same number is Krino's entry gate: below your configured Min Conviction to Trade, no plan is built. By the time a Buy signal reaches sizing it has cleared that bar, and Krino re-scales it: 0 at the gate, 1 at maximal agreement.
Size Fraction always lands between 0.5× and 1.0×, so it can only shrink the Pure Risk-Based quantity. The confidence factor is 1.0 when the symbol has a strong track record (a win rate of 60% or more over at least five trades, with a contained drawdown) and drops to as low as 0.42 when it doesn't. Krino rounds down once, at the end.
| Risk-capped quantity = 480 / 17 (before rounding) | 28.24 |
| Confidence factor (strong track record) | 1.0 |
| Raw conviction (rule agreement) | 0.82 |
| Your min conviction to trade | 0.40 |
| Normalized = (0.82 − 0.40) / (1 − 0.40) | 0.70 |
| Size fraction = 0.5 + (0.5 × 0.70) | 0.85 |
| Shares = floor(28.24 × 1.0 × 0.85) | 24 |
| Position value | €4,920 |
| Maximum loss | €408 |
| Potential profit | €744 |
- Sizes down automatically when your own rules disagree with each other
- Never exceeds the Pure Risk-Based ceiling
- Only as good as the rules and weights you configured
- Two setups with identical risk can size differently
In the screenshot above it's the Conviction-Adjusted row, marked Selected because it's Krino's default: 24 shares, 0.85 of the risk-based quantity. With maximum conviction and a strong track record it would match Pure Risk-Based; weaker agreement pushes it lower. Note its Low fee-efficiency badge, too: at €4,920 the position is just under the €5,000 line where Krino starts warning that fixed costs weigh on a small trade.
Conviction-Adjusted sizing is a discount, not a boost — it trims the risk-based quantity down when your own rules only barely agree, it never sizes you up beyond what pure risk already allows.
3Exposure-Based Sizing
Start from how much of your portfolio this idea deserves, not from the stop.
| Exposure % | 10% |
| Target position = 100,000 × 10% | €10,000 |
| Shares = 10,000 / 205 | ≈ 48 |
| Maximum loss | ≈ €816 |
| Potential profit | ≈ €1,488 |
- Simple and intuitive
- Produces more meaningful position sizes
- Money at risk varies trade to trade
- A wide stop quietly means a bigger bet
In the screenshot above it's the middle row: 48 shares and 0.82% of the portfolio at risk, classified Moderate. It ignores the stop entirely, so with a tighter stop the same 48 shares would risk less, and with a wider one more.
Exposure-Based sizing caps how big a bet gets in portfolio terms — but two trades at the same exposure % can carry very different amounts at risk if their stops sit at different distances.
4EV-Scaled Sizing
Not every setup deserves the same size. A conviction multiplier scales the position up or down with setup strength:
| Low conviction | 0.5× |
| Normal | 1.0× |
| Strong | 1.5× |
| Exceptional | 2.0× |
Applied to our Exposure-Based baseline of 48 shares, on a Strong setup:
| Base position (Exposure-Based) | 48 shares |
| Strong setup: 48 × 1.5 | 72 shares |
| Maximum loss | ≈ €1,224 |
| Potential profit | ≈ €2,232 |
- Aligns capital with your best ideas
- Rewards a genuine edge
- Only works if conviction is scored consistently
- Can become subjective without a fixed rule
That's the EV-Scaled row in the screenshot above — larger than Exposure-Based, smaller than Aggressive.
EV-Scaled sizing only helps if "strong setup" means the same thing every time you use it — otherwise it's conviction-based sizing wearing a formula's clothes.
5Aggressive Sizing
Some traders concentrate capital in their highest-conviction ideas, accepting bigger swings for a bigger payoff.
| Max position exposure | 40% of portfolio |
| Target position = 100,000 × 40% | €40,000 |
| Shares = 40,000 / 205 | ≈ 195 |
| Position value | €39,975 |
| Maximum loss | €3,315 |
| Potential profit | €6,045 |
- Meaningful upside when you're right
- A handful of winners can carry a whole portfolio
- Drawdowns can be severe
- Requires real emotional discipline to hold through
It's the largest row in the screenshot above — the whole €40,000 allocation in one trade, with 3.32% of the portfolio at risk — and the only one flagged with an Aggressive risk badge.
Aggressive sizing isn't wrong — but it's a deliberate, bounded exception, not a default. Know your ceiling before you approach it.
All five, side by side
Same entry, stop and take-profit. Only the share count changes, and with it the risk.
| Approach | Shares | Position Value | Maximum Loss | Potential Profit | Portfolio Risk % | Risk / Reward |
|---|---|---|---|---|---|---|
| Pure Risk-Based | 28 | €5,740 | €476 | €868 | 0.48% | 1.82 |
| Conviction-Adjusted Default | 24 | €4,920 | €408 | €744 | 0.41% | 1.82 |
| Exposure-Based | 48 | €9,840 | €816 | €1,488 | 0.82% | 1.82 |
| EV-Scaled Strong | 72 | €14,760 | €1,224 | €2,232 | 1.22% | 1.82 |
| Aggressive | 195 | €39,975 | €3,315 | €6,045 | 3.32% | 1.82 |
The Risk/Reward ratio never changes: sizing doesn't touch entry, stop or target, only how much you have exposed. The figures match the screenshot above, with the risk badge climbing from Conservative to Aggressive as the share count grows.
Size your own trade four ways
| Approach | Shares | Position Value | Maximum Loss | Portfolio Risk % | Risk budget |
|---|---|---|---|---|---|
| Pure Risk-Based | – | – | – | – | – |
| Exposure-Based | – | – | – | – | – |
| EV-Scaled | – | – | – | – | – |
| Aggressive | – | – | – | – | – |
- Pure Risk-Based — new to systematic trading, or rebuilding discipline after a rough stretch.
- Conviction-Adjusted — want Krino's default: risk-capped sizing that also discounts for a weak or thin edge.
- Exposure-Based — want simple, consistent position sizes across a watchlist.
- EV-Scaled — have a track record and want capital to follow conviction, deliberately.
- Aggressive — concentrated, high-conviction investing with a stomach for drawdowns.
Common mistakes
- Sizing on emotion — buying more because a stock "feels" right, not because a rule said so.
- Sizing on conviction alone — skipping the risk math because you're "sure" about this one.
- Ignoring stop distance — the same share count means very different risk depending on how far the stop is.
- One size for every trade — treating a high-conviction setup and a speculative punt identically.
- Positions too small to matter — sizing so conservatively that fees and slippage eat the edge.
A framework, not a formula
No single number makes a trade safe. Three things have to work together:
| Maximum exposure | How big any one symbol can get, portfolio-wide. |
| Maximum risk | How much you're willing to lose if the stop is hit. |
| Sizing model | The formula that turns those limits into a share count. |
Change one without the others and the plan drifts: a generous exposure cap with a careless risk % still produces a careless trade.
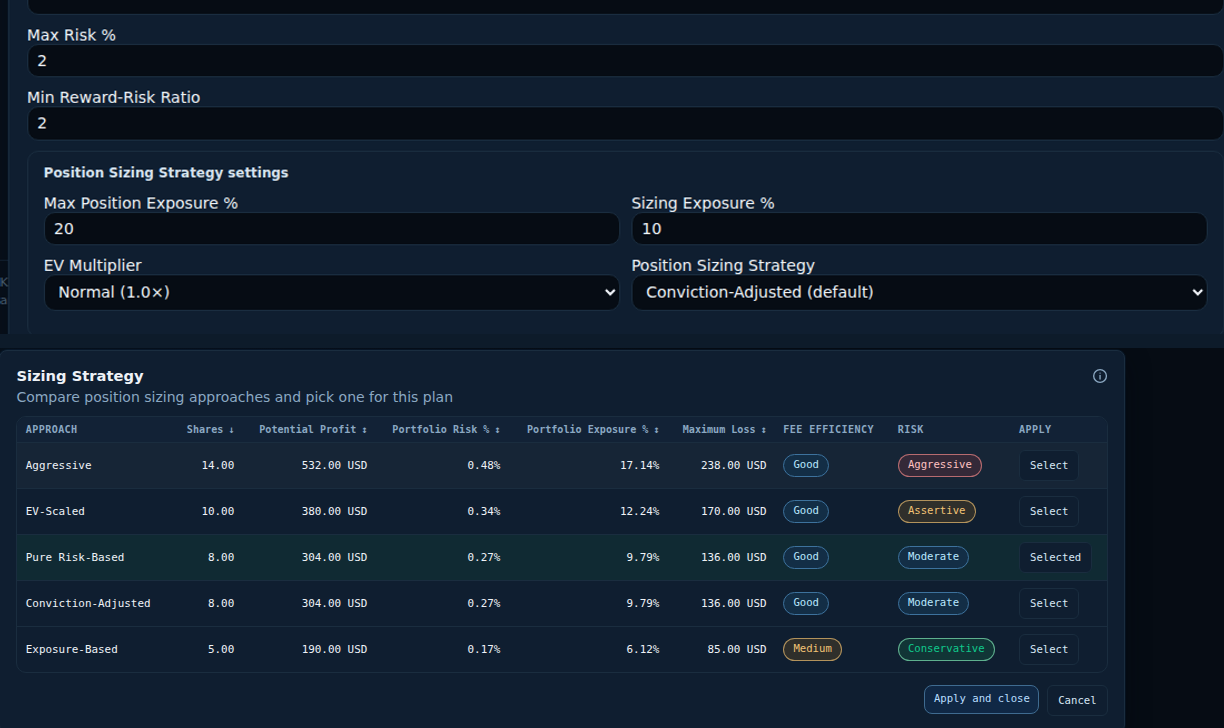
How Krino helps
Everything above is arithmetic you can do by hand. Krino does it automatically, so the comparison is in front of you:
- Compares all five sizing models side by side for the same trade
- Checks the resulting risk against your account and per-position budget before you can act
- Shows fee efficiency and a risk classification for every approach, not just the one you picked
- Turns the whole thing into one structured, timestamped trade plan you can revisit later
None of it replaces your judgment about which stock to trade. It makes sure the size was decided, not guessed.
Now check the size against a risk budget.
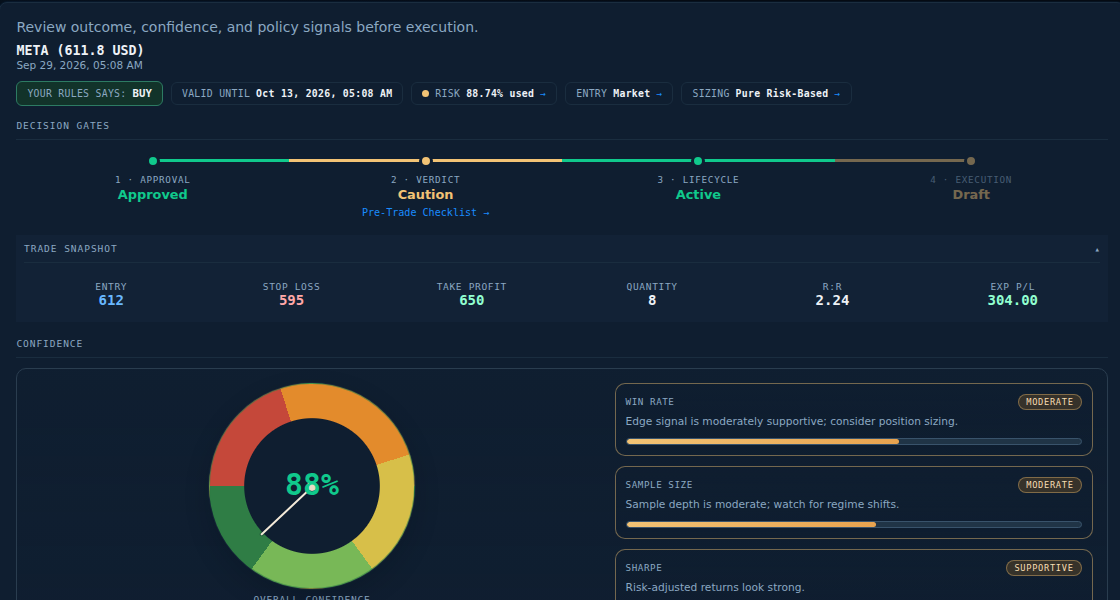
Krino sizes every trade five ways, checks the result against your risk budget and blocks plans that break it. The demo opens in your browser — no signup, no email, no card.
The question that actually matters
Not "is this a good stock?" That question has no risk in it.
The better question: "How much should I buy if I'm wrong?"
Good trading is selection, risk definition and position sizing, applied consistently. Before your next trade, size it on paper first and see which model you'd be comfortable holding through a loss.
Size your next trade before you place it.
Open a sample META trade and see all five share counts, the money at risk and whether the limits allow it. No signup needed.
Krino executes rules and risk limits you configure. It is not personalized investment advice. Trading involves risk of loss. You are solely responsible for your own trading decisions. The worked example in this article uses illustrative prices, not a recommendation or real market data for SAP; the screenshots show that same example set up in Krino.